Carbon Markets and India's Green Transition: Opportunities, Challenges, and Strategy
#GS-3 #Economy #Infrastructure #Environment #Climate Change #Sustainable Development #Current Events #National #Conservation
Key takeaways
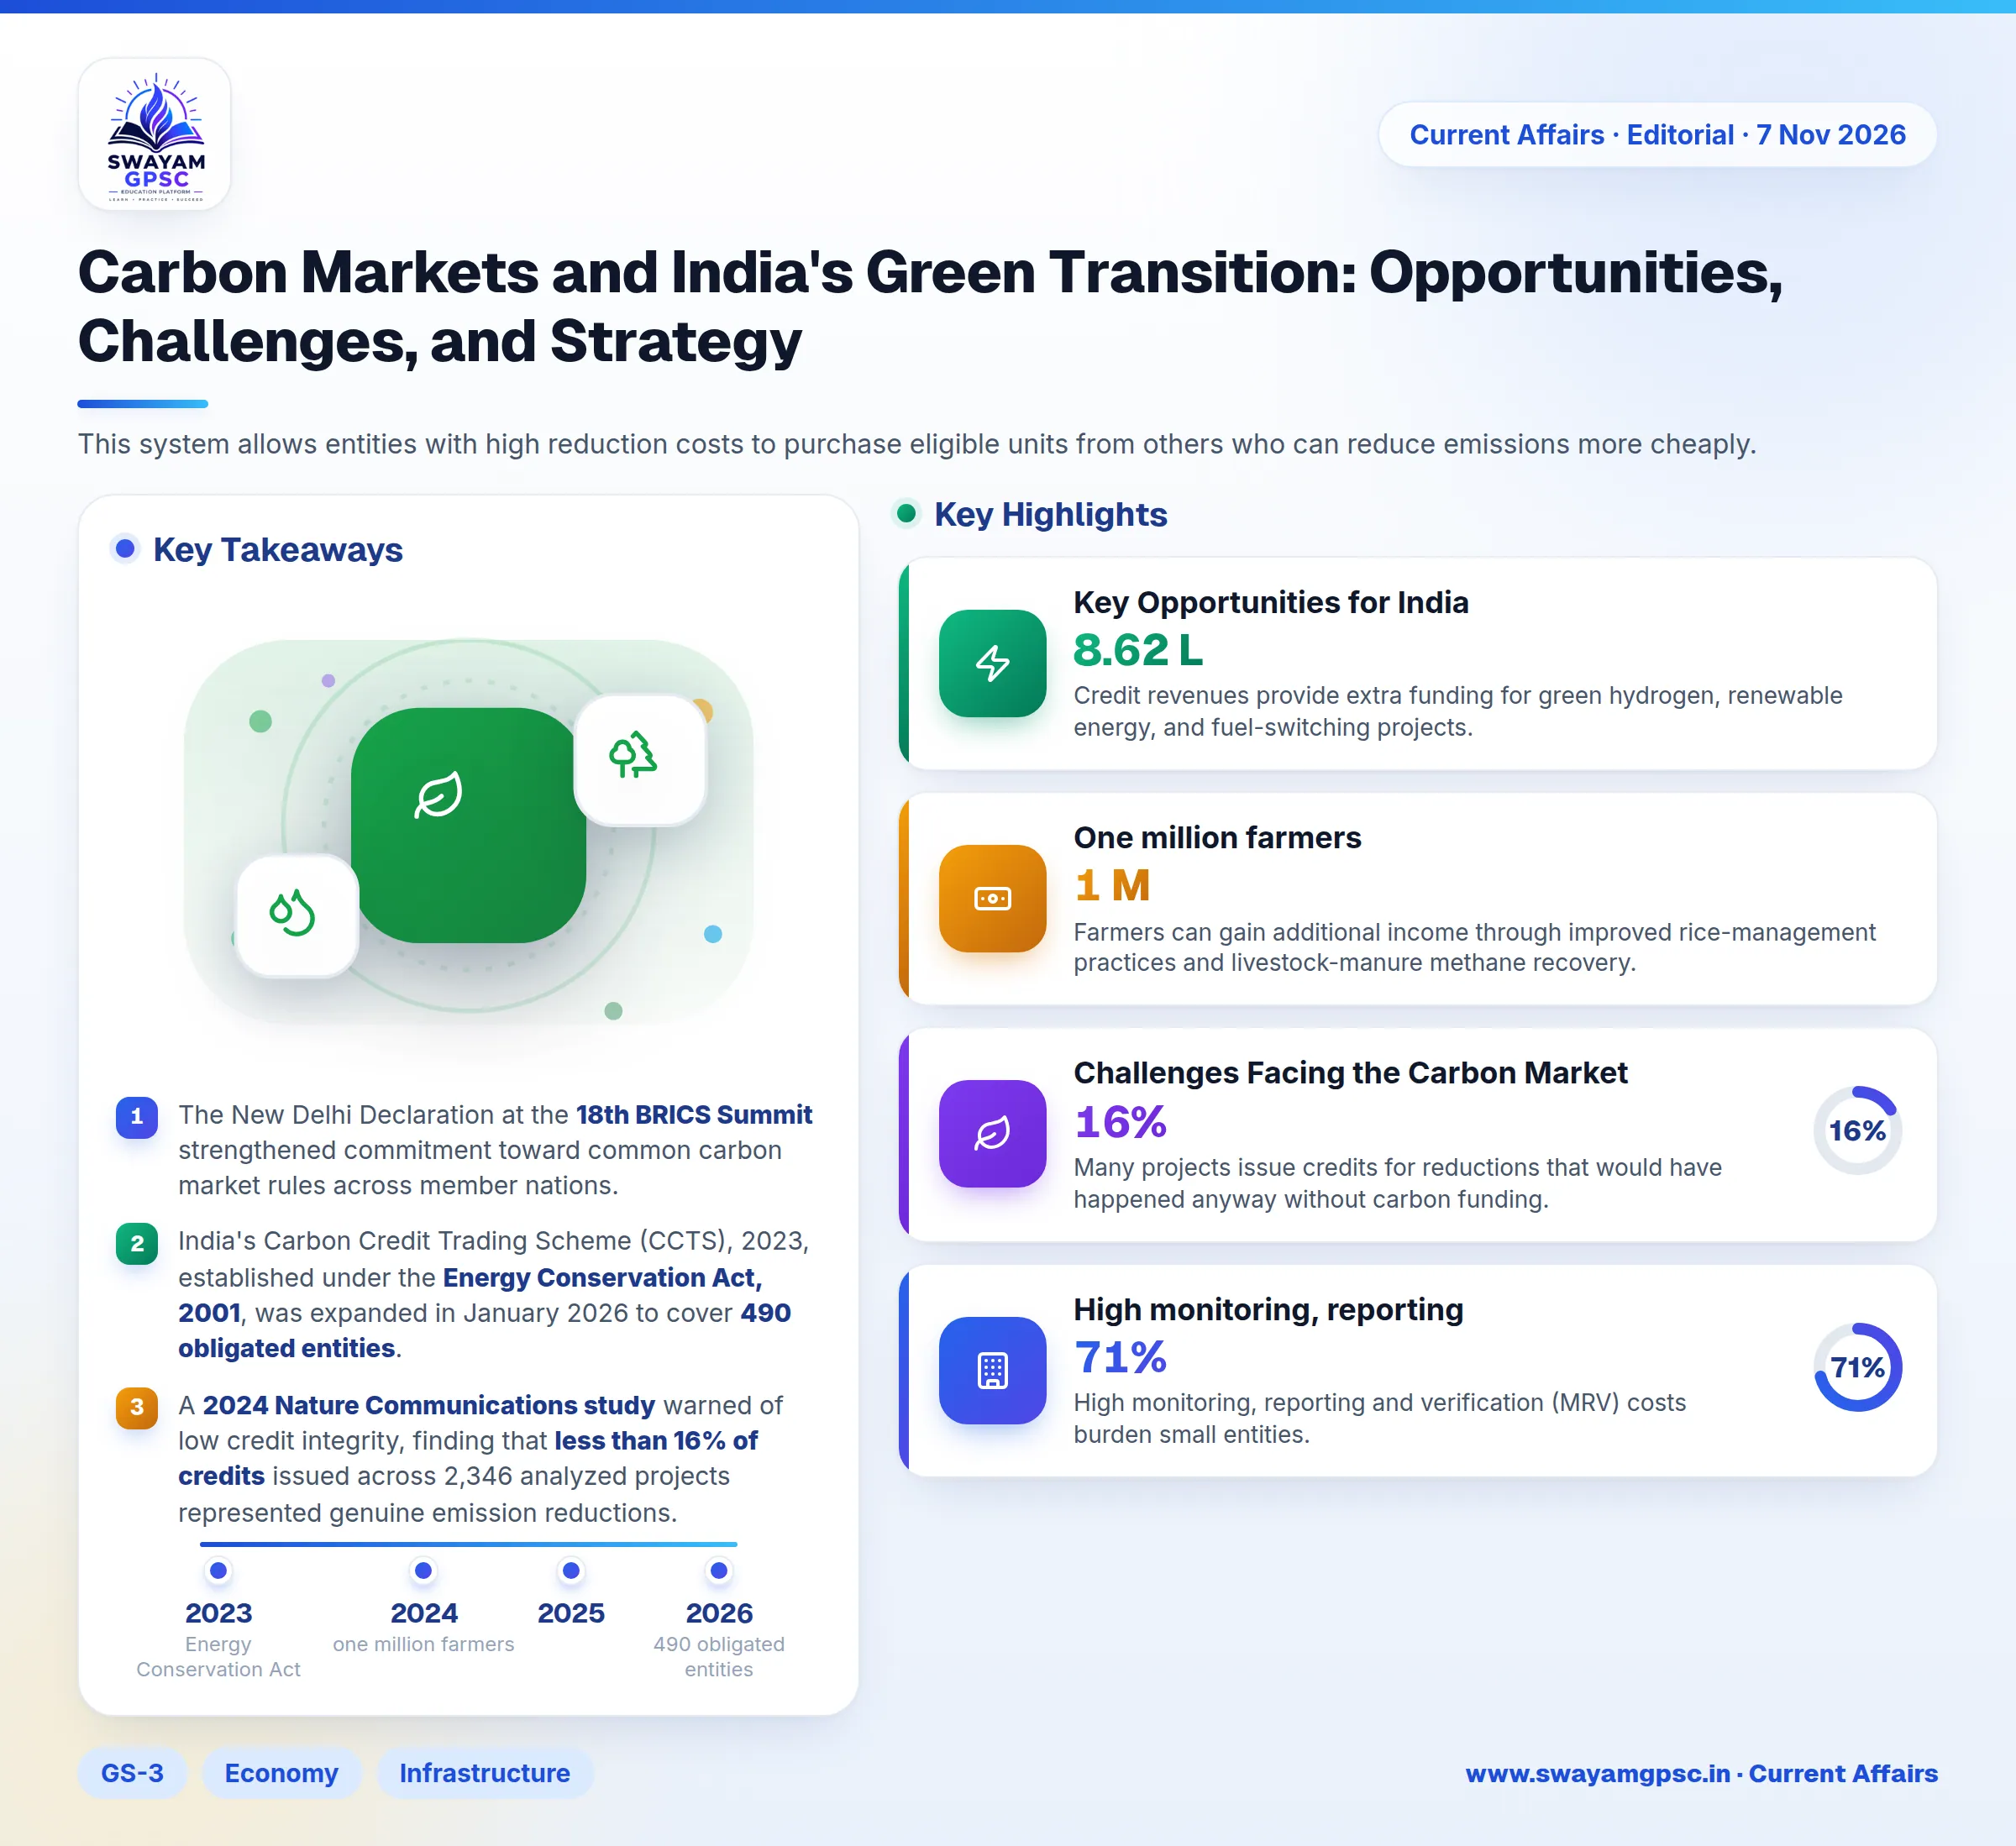
- The New Delhi Declaration at the 18th BRICS Summit strengthened commitment toward common carbon market rules across member nations.
- India's Carbon Credit Trading Scheme (CCTS), 2023, established under the Energy Conservation Act, 2001, was expanded in January 2026 to cover 490 obligated entities.
- A 2024 Nature Communications study warned of low credit integrity, finding that less than 16% of credits issued across 2,346 analyzed projects represented genuine emission reductions.
- Globally, oversupply poses a major pricing challenge, with the World Bank reporting an unretired credit pool approaching one billion tonnes in 2024.
- India has targeted major green initiatives, including incentives for 8.62 lakh tonnes per annum of green-hydrogen production capacity and protecting 4,992 sq km of mangrove cover recorded in ISFR 2023.
Why in News
- The New Delhi Declaration at the 18th BRICS Summit reaffirmed the commitment to the BRICS Carbon Markets Partnership. This signals a shift toward common global rules for measuring, reporting, and verifying emissions reductions.
- With eight BRICS members currently operating voluntary carbon markets, carbon trading offers India strong opportunities. It can help mobilize climate finance, accelerate industrial decarbonization, and boost green competitiveness if market integrity is maintained.
Understanding the Carbon Market
- A carbon market is a trading system for emissions allowances or carbon credits. It gives greenhouse gas emissions a direct financial value.
- This system allows entities with high reduction costs to purchase eligible units from others who can reduce emissions more cheaply.
- The primary goal of this mechanism is to encourage cost-effective decarbonization and channel funds toward clean technologies.
- An emissions allowance permits an entity to emit one tonne of carbon dioxide equivalent (tCO₂e) inside a regulated system.
- A carbon credit represents one tCO₂e of verified emissions reduction or removal. For example, a methane-capture project delivering 1,000 tCO₂e of verified reductions receives 1,000 credits.
- Compliance markets operate under strict legal mandates. In a cap-and-trade system, regulators set an overall emissions cap and issue allowances that covered entities can trade.
- Other compliance systems use emissions-intensity benchmarks, rewarding companies that produce fewer emissions per unit of output. However, intensity systems do not automatically cap total emissions because total production can still grow.
- In voluntary carbon markets, organizations purchase credits voluntarily without any legal requirement to offset their emissions.
- Eligible voluntary projects include methane capture and forest restoration. These projects undergo strict monitoring, reporting and verification (MRV) before credits are issued and retired to prevent resale.
- Article 6 of the Paris Agreement sets the international framework for carbon trading. Article 6.2 covers bilateral trading of Internationally Transferred Mitigation Outcomes (ITMOs), while Article 6.4 creates a UN-supervised crediting mechanism.
- Under Article 6, corresponding adjustments ensure that double counting does not happen between buyer and seller countries, while Article 6.8 governs non-market cooperation.
- India created its Carbon Credit Trading Scheme (CCTS), 2023 under the amended Energy Conservation Act, 2001. It features both compliance and voluntary offset mechanisms.
- Under India's CCTS, obligated entities performing better than their GHG targets earn Carbon Credit Certificates. BEE administers the scheme, Grid Controller of India operates the registry, and CERC regulates trading.
Key Opportunities for India
- Carbon markets reward Indian factories that cut emissions faster than required. The January 2026 update expanded compliance coverage to 490 obligated entities across cement, aluminium, textiles, and refining.
- Credit revenues provide extra funding for green hydrogen, renewable energy, and fuel-switching projects. BEE has approved methodologies for hydrogen production, where India has already awarded incentives for 8.62 lakh tonnes per annum of green-hydrogen production capacity.
- Farmers can gain additional income through improved rice-management practices and livestock-manure methane recovery. For instance, a World Bank-supported Uttar Pradesh agriculture project approved in December 2024 targets one million farmers using low-methane techniques.
- Aggregating small farms through FPOs and cooperatives makes carbon verification affordable for smallholders.
- Municipalities can earn carbon revenues from landfill-methane capture and compressed biogas (CBG). Indore's municipal Bio-CNG facility demonstrates this potential by producing 17,000 kg of Bio-CNG daily.
- India can attract carbon finance for mangrove restoration and afforestation, protecting coastal ecology and local livelihoods. ISFR 2023 recorded 4,992 sq km of mangrove cover, and BEE has approved targeted restoration methodologies.
- Bilateral agreements under Article 6.2 bring foreign investment and technology. The India-Japan Memorandum of Cooperation on the Joint Crediting Mechanism signed in August 2025 exemplifies this cooperation.
- Tracking emissions for carbon markets prepares Indian exporters for global green regulations like the EU's Carbon Border Adjustment Mechanism (CBAM), which targets steel, aluminium, cement, fertilisers, and hydrogen.
- The expanding market builds an ecosystem for carbon accounting, project validation, verification, and remote sensing. BEE's accredited-verifier register from October 2026 includes prominent bodies like Bureau Veritas India and FICCI.
Challenges Facing the Carbon Market
- Many projects issue credits for reductions that would have happened anyway without carbon funding. A 2024 Nature Communications study covering 2,346 projects found that less than 16% of credits represented real emission cuts.
- High monitoring, reporting and verification (MRV) costs burden small entities. A 2025 CEEW study found that 71% of unregistered Indian energy-industry projects exceeded the rest-of-Asia registration benchmark of 427 days.
- Excess credit supply depresses prices globally. The World Bank's 2025 assessment noted that the global pool of unretired credits approached one billion tonnes in 2024, leading to further price drops in 2025.
- Forest carbon storage faces non-permanence risks from natural hazards. A parliamentary reply in December 2025 reported 1,808.90 sq km of assessed burnt area in Uttarakhand during November 2023-June 2024.
- Fragmented domestic and international rules create regulatory confusion. BEE explicitly prohibits concurrent registration under other carbon-market or relevant certificate mechanisms to prevent double claims.
- Carbon contracts can exploit local communities by separating land ownership from credit rights. CSE's 2023 study of an Araku Valley project highlighted developers taking credit rights for a 20-year crediting period.
- Exporting cheap carbon credits abroad can compromise India's own Nationally Determined Contribution (NDC) under the UNFCCC, making future domestic decarbonization much costlier.
- Intensity-based targets can lead to greenwashing. If intensity drops by 10% but production grows by 20%, absolute emissions still rise by 8%.
Way Forward
- India must establish dynamic baselines and scientific reviews. Applying benchmarks like the Integrity Council for the Voluntary Carbon Market's assessment framework can help suspend methodologies that inflate reductions.
- Developing open digital MRV protocols using sensors and satellite data can lower costs for FPOs and MSMEs.
- The government can pilot carbon contracts for difference to guarantee stable carbon prices for high-priority industrial decarbonization projects.
- Building a public credit registry with automated checks against renewable-energy certificate registries will prevent double-counting and build trust.
- Establishing standardized benefit-sharing contracts in local languages will protect land rights and ensure fair revenue distribution for local communities.
- Markets must separate temporary biological storage from permanent removals, applying risk-weighted buffer contributions to handle carbon reversal risks.
- Regulators should link intensity targets with sector-specific absolute-emission trajectories so efficiency gains genuinely cut total national emissions.
- India should publish clear multi-year authorization envelopes for international credit transfers to protect national targets under its NDC.
Conclusion
- Developing a robust carbon market is essential to balance India's industrial growth with its climate commitments.
- By fixing additionality issues, lowering digital MRV costs, and creating transparent benefit-sharing rules, India can build a resilient carbon market that attracts global climate finance.