Decade Review of India's 2016 Demonetisation
#GS-2 #GS-3 #Government Policies & Interventions #Fiscal Policy #Growth #Banking #Current Events #National
Key takeaways
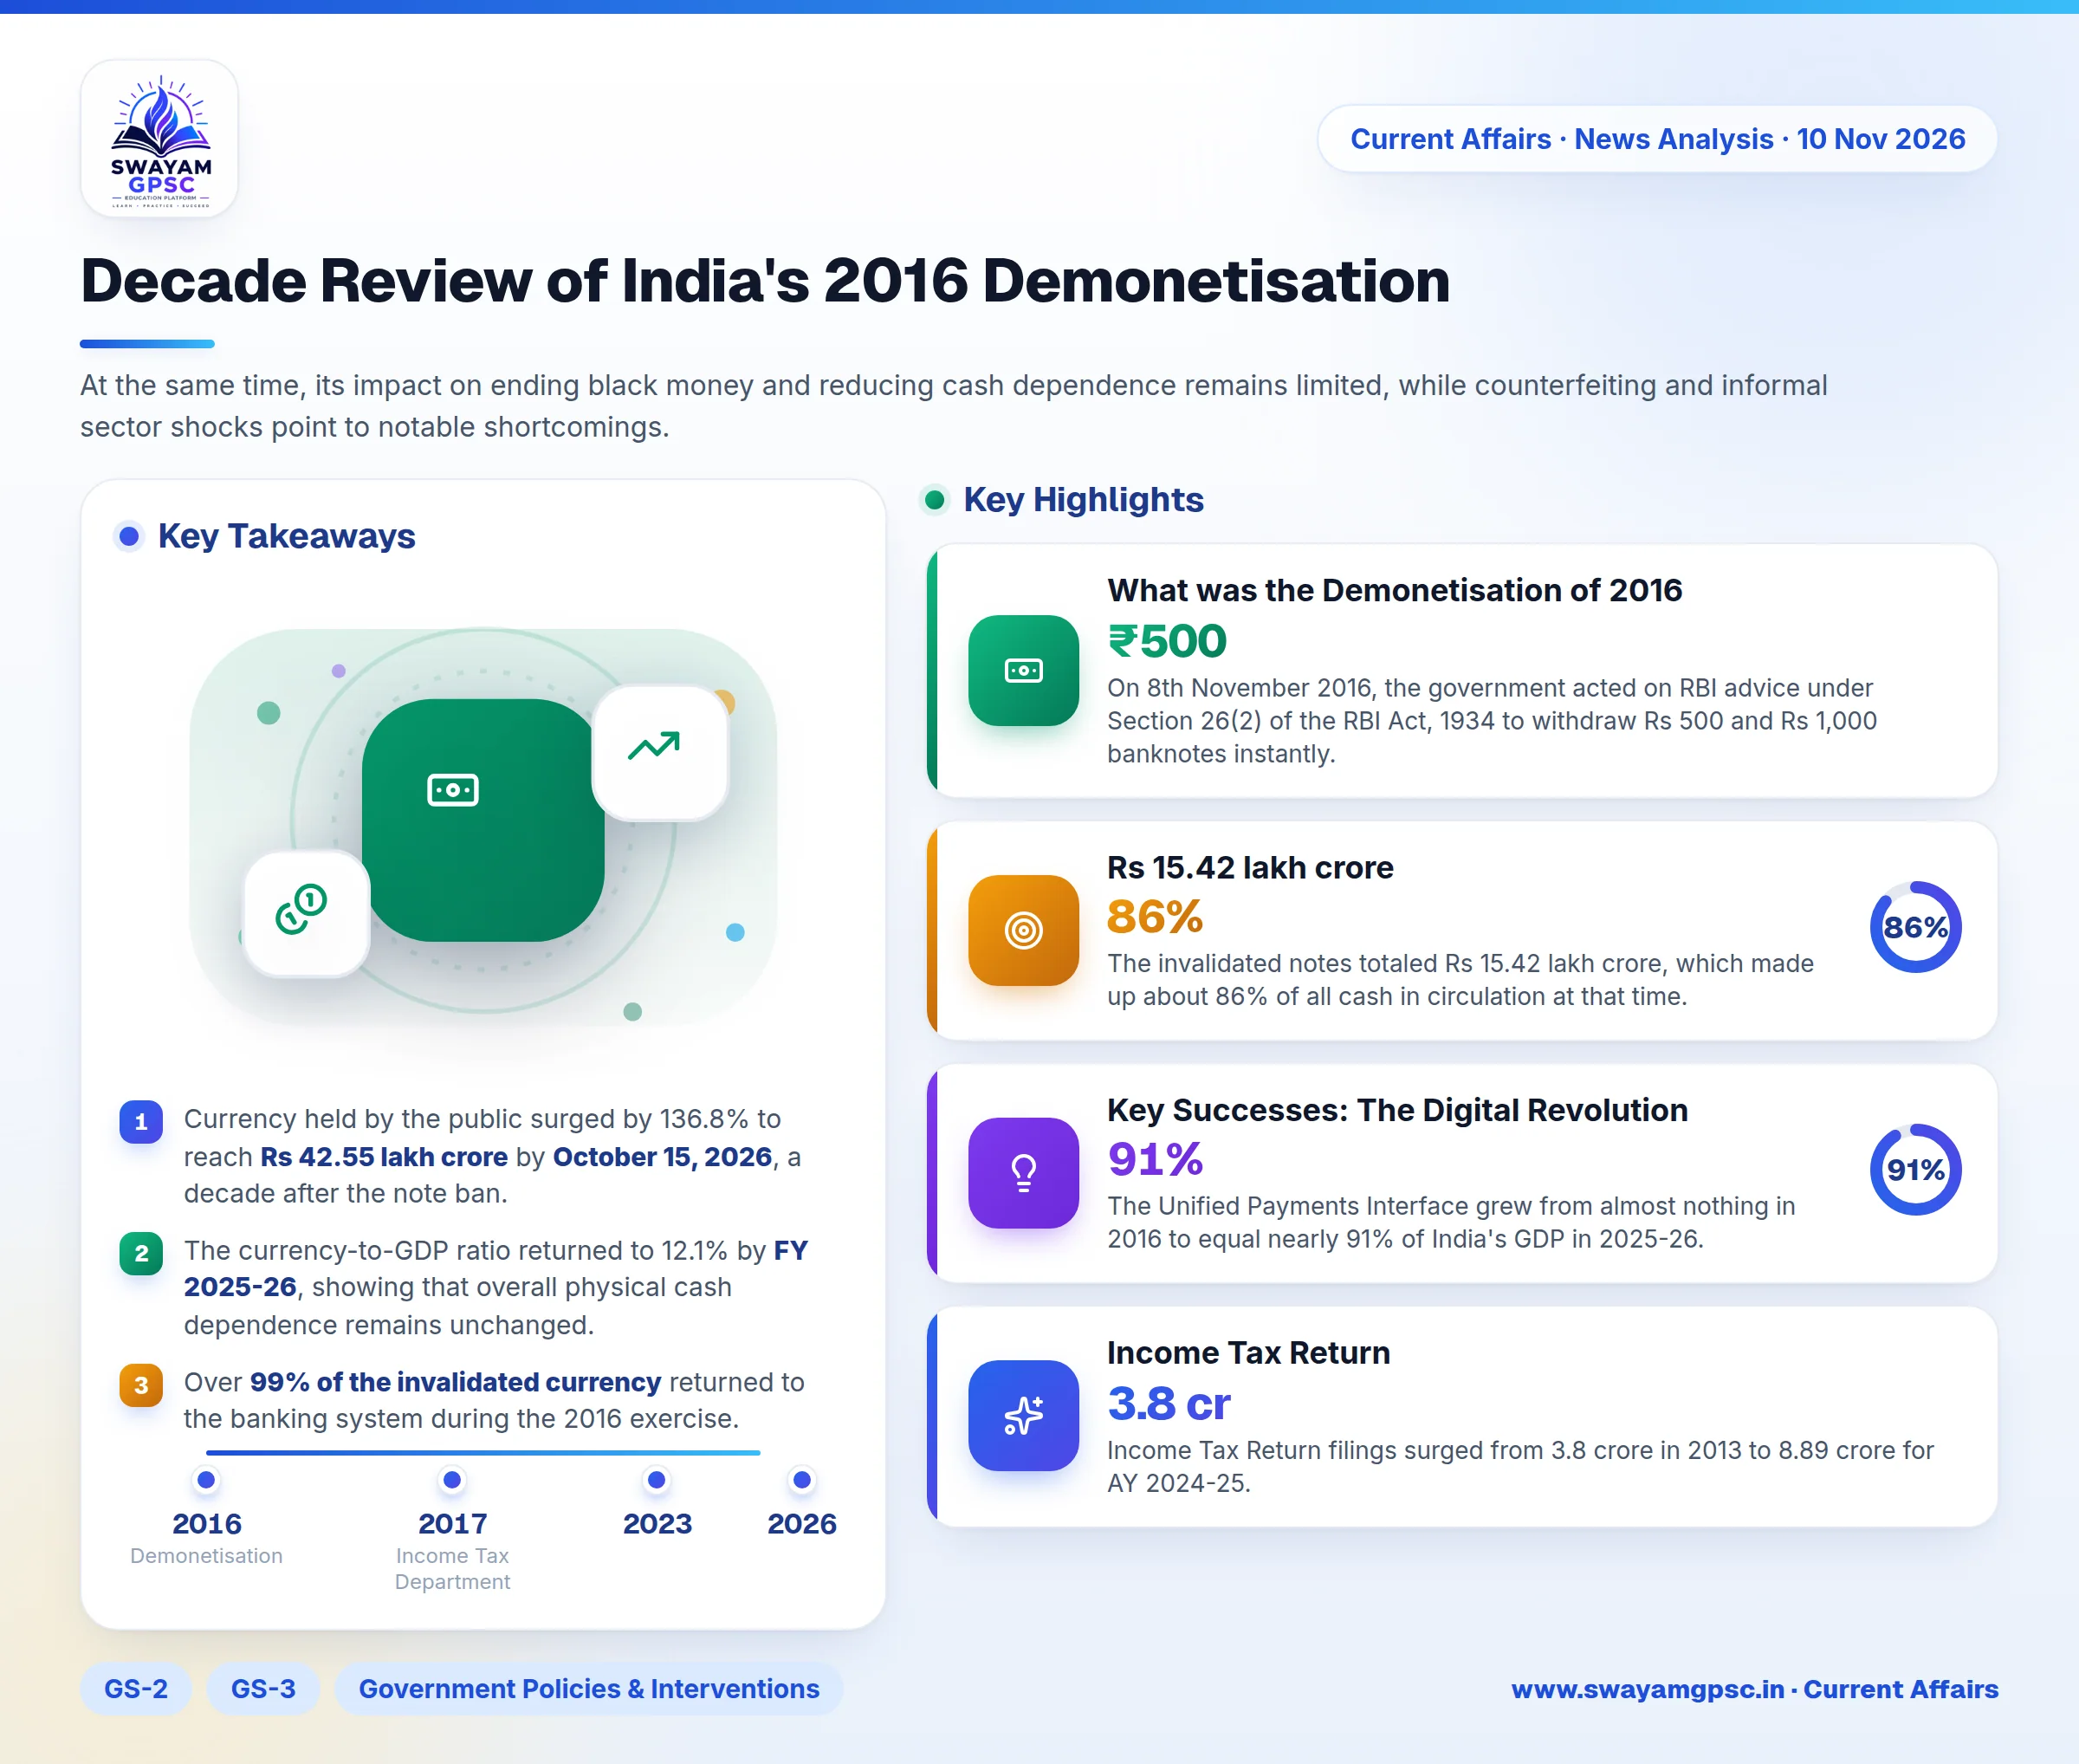
- Currency held by the public surged by 136.8% to reach Rs 42.55 lakh crore by October 15, 2026, a decade after the note ban.
- The currency-to-GDP ratio returned to 12.1% by FY 2025-26, showing that overall physical cash dependence remains unchanged.
- Over 99% of the invalidated currency returned to the banking system during the 2016 exercise.
- Counterfeiting of new currency worsened over time, with the RBI detecting 1.42 lakh fake Rs 500 notes in 2025-26.
- Total digital payments across India reached Rs 3,251.04 lakh crore in FY 2025-26.
Why in News
- The Demonetisation exercise of 2016 completed its ten-year milestone on 8th November 2026.
- Data from the Reserve Bank of India shows a mixed legacy that includes massive digital payment growth alongside enduring cash usage and rising currency counterfeiting.
Summary
- The note ban acted as a major catalyst for India's digital payment ecosystem, improved tax compliance, and pushed economic formalisation.
- At the same time, its impact on ending black money and reducing cash dependence remains limited, while counterfeiting and informal sector shocks point to notable shortcomings.
What was the Demonetisation of 2016
- Demonetisation means stripping a specific currency unit of its legal tender status so that it is retired from active circulation.
- On 8th November 2016, the government acted on RBI advice under Section 26(2) of the RBI Act, 1934 to withdraw Rs 500 and Rs 1,000 banknotes instantly.
- The invalidated notes totaled Rs 15.42 lakh crore, which made up about 86% of all cash in circulation at that time.
- The sudden step aimed to remove black money, fight counterfeit notes, block terror funding, and move India toward a digitized economy.
- The Income Tax Department started Operation Clean Money in 2017 through the CBDT to examine suspicious cash deposits.
- This operation used data analytics to compare bank deposits with past taxpayer profiles to expand the tax base.
- A five-judge Supreme Court Bench upheld the move by a 4:1 majority in *Vivek Narayan Sharma v. Union of India (2023)*.
- Justice B.V. Nagarathna dissented by arguing that such a massive step needed a direct Act of Parliament instead of an executive notification.
- The RBI later withdrew Rs 2,000 banknotes in 2023 under its Clean Note Policy, though those notes kept their legal tender status.
Historical Examples of Demonetisation
- India first demonetized currency in 1946 by scrapping high-value notes to tackle black money from World War II profiteering.
- The government again demonetized high-denomination notes in 1978 following suggestions from the Wanchoo Committee (1970).
- Globally, the United States withdrew notes above USD 100 in 1969 to fight organised crime without disrupting everyday trade.
- The Soviet Union abruptly withdrew 50 and 100-ruble notes in 1991, which caused severe public distrust during its final months.
Key Successes: The Digital Revolution
- The note ban accelerated the mass adoption of Digital Public Infrastructure across the country.
- The Unified Payments Interface grew from almost nothing in 2016 to equal nearly 91% of India's GDP in 2025-26.
- Tax compliance improved as millions of unrecorded transactions moved into formal banking channels.
- Income Tax Return filings surged from 3.8 crore in 2013 to 8.89 crore for AY 2024-25.
- The sudden shock temporarily paralyzed cash-based financial networks used by hawala operators, terror groups, and Left-Wing Extremism.
Key Limitations and Unmet Objectives
- Currency with the public stood at 11.9% of GDP in 2015-16, compared to 12.1% in 2025-26, showing little change in relative cash demand.
- Total banknotes in circulation jumped from Rs 16.4 lakh crore in March 2016 to over Rs 41.2 lakh crore by March 2026.
- Data from the RBI shows that counterfeiting of the new high-security notes has risen significantly over time.
- The RBI reported a 37.3% increase in counterfeit Rs 500 notes in 2024-25, reaching 1.42 lakh fake notes in 2025-26.
- Over 99% of the invalidated currency returned to banks, proving that black money is mostly stored in hard assets like real estate and gold.
- Security printing expenditure for the RBI jumped from Rs 3,421 crore in 2015-16 to Rs 7,965 crore in 2016-17.
- The sudden cash squeeze severely hurt the informal sector, causing job losses and supply chain disruptions for MSMEs and daily wage earners.
Measures Needed for Effective Currency Management
- Commercial banks and the central bank should use artificial intelligence sorting machines at currency chests to catch fake notes quickly.
- The rollout of the digital rupee should focus on offline access, privacy safeguards, and interoperability.
- The Enforcement Directorate and Financial Intelligence Unit must link databases through Project Insight to track hidden wealth in real estate and gold.
- Regulators should keep merchant discount rates low and promote offline digital tools like UPI Lite and NFC to support small businesses.
- The RBI should pilot polymer notes in lower denominations because they last longer and resist counterfeiting.
Conclusion
- The 2016 demonetisation acted as a major catalyst for formalizing the Indian economy.
- Sustained institutional effort and technological integration are now necessary to use this digital foundation for achieving inclusive economic growth.
Prelims in Focus: Rising Cash Circulation and Digital Trends
- Currency held by the public surged to Rs 42.55 lakh crore by October 15, 2026, which is a 136.8% increase over pre-demonetisation levels.
- The currency-to-GDP ratio dropped after the note ban, spiked to 14.4% during the 2020-21 pandemic, and settled back at 12.1% in FY 2025-26.
- Total digital payments across India reached Rs 3,251.04 lakh crore in FY 2025-26.
- Credit cards, debit cards, and wallets accounted for 151,611 lakh transactions worth Rs 30.31 lakh crore during the same fiscal year.
- Nominal GDP expansion, deep reliance on the informal workforce, and precautionary savings continue to drive high physical cash demand.